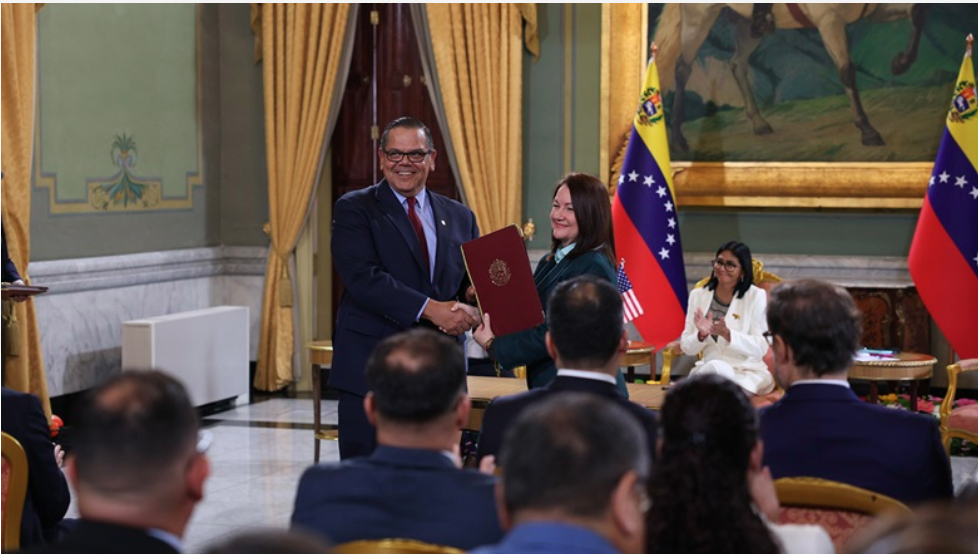
Photo: Mariano Vela (left), the president of Chevron Venezuela, recently met with Venezuela’s Minister of Petroleum and Hydrocarbons Paula Henao (standing, right) in Caracas. Source: https://www.chevron.com/newsroom/2026/q3/a-turning-point-for-energy-in-venezuela
Deepseek Binary response:
The resolution source and corroborating market data all point the same way: Brent is currently around $110/bbl, and it has not traded below $50 at any point in 2026. The lowest 2026 weekly low cited is about $59.73, and the trailing 52-week low is about $58.69. To resolve Yes from here, Brent would need to collapse by roughly 55% in about ten weeks. No authoritative forecast in the research places Brent anywhere near $50 in Q4 2026; official and bank forecasts cluster around $90–$114 for Q4 2026 and around $84 or higher for 2027.
A Yes outcome would require a very large tail event: a rapid, comprehensive de-escalation in the Middle East and/or a severe global demand shock, side by side with faster OPEC+ supply normalization and possibly a flash-crash-type move. These are possible in oil markets, but must be heavily discounted given the short remaining window and the current tight physical market. The main assumptions that could change the forecast are: (1) a sudden war-ending supply normalization could remove the geopolitical premium faster than expected; (2) a severe global recession or financial crisis could cause demand destruction and forced liquidation; and (3) an erroneous or anomalous Trading Economics print could create a brief false trigger. Even allowing for these, the required move is so far beyond current 2026 behavior and forward guidance that the probability remains low single digits.
Shorter remaining interval through late November: extremely low, likely under 1%. Through December 31: still very low, around 2%. A longer horizon into Q1 2027 would be somewhat higher because there is more time for the forecast 2027 surplus and demand weakness to matter, but that is outside the resolution window.
Data sufficiency: Sufficient
Probability: 2%
Perplexity response:
10 citations
1. “Brent oil Price — Chart — Historical Data — News” — Trading Economics; live page updated Oct. 20, 2026. Description: The designated resolution source, showing the live Brent CFD quote, historical range, news and model forecasts. Summary: The resolution page showed Brent at $110.50/bbl on Oct. 20, 2026, up 0.87% d/d, 10.13% m/m and 80.21% y/y, with an intraday move above $111 to a five-month high. Trading Economics put its 4Q26 model forecast at $113.86 and its 12-month estimate at $130.36, both far above the $50 trigger. The current quote is more than double the $50 threshold, so the resolution condition is nowhere near current trading.
2. “Live Brent Oil Futures CFD Prices & Online Trading Charts” — Markets.com; weekly data through Oct. 19, 2026. Description: Weekly Brent futures/CFD price history with 52-week high, low and current quote. Summary: Markets.com’s weekly table showed a 52-week range of $58.69–$119.46 and a latest close of $110.17 on Oct. 19, 2026. Within calendar 2026, the lowest weekly low shown was $59.73 in the week of Jan. 5; other notable lows were $62.73 in mid-January, $70.10 in late June and $70.98 in early July. Because even the trailing 52-week low is $8.69 above $50, this history is inconsistent with any sub-$50 Brent print in 2026 to date.
3. “Brent Crude Oil Spot Price (Monthly, I:BCOSPNM)” — YCharts; data last updated Oct. 7, 2026. Description: Monthly Dated Brent spot-price series from IMF data, useful for seasonality and monthly averages. Summary: Monthly Dated Brent averages were $64.59 in January, $69.41 in February, $99.40 in March, $102.81 in April, $103.84 in May, $84.49 in June, $83.73 in July, $88.07 in August and $102.02 in September 2026. The series shows a violent war-driven repricing rather than a move toward $50, with the monthly average never below $64.59 in 2026. September was up 15.84% m/m and 50.89% y/y.
4. “Short-Term Energy Outlook: Prices” — U.S. Energy Information Administration; released Oct. 6, 2026; forecast finalized Oct. 1. Description: The U.S. government’s official short-term oil-price forecast and assumptions. Summary: The October STEO forecasts Brent to average $96/bbl in 2026 and $84/bbl in 2027, versus $69/bbl in 2025. It raised the 4Q26 forecast by $14 to $105/bbl, assuming Middle East flows remain constrained through year-end, and expects the spot price to fall only to $84/bbl next year. The nearest quarterly forecast is more than double the $50 threshold, and the annual forecast leaves a very wide buffer.
5. “Oil Market Report — October 2026” — International Energy Agency; published Oct. 13, 2026. Description: The IEA’s monthly global oil demand, supply, inventory and refining assessment. Summary: The IEA estimated 2026 demand at 102.4 mb/d, down 2.6 mb/d y/y, and supply at 100.7 mb/d, down 5.8 mb/d. It said balances would remain in deficit through end-2026, with middle-distillate tightness persisting into 2027, and noted Brent futures around $107/bbl when published, up 13% since early September. That supply-demand framing supports elevated prices and warns that renewed Gulf attacks could cause further turmoil before an eventual 2027 surplus.
6. “Hormuz closure and related production outages are key drivers in EIA’s latest forecast” — U.S. EIA; published Apr. 7, 2026. Description: EIA’s April 2026 analysis of the Strait of Hormuz closure and its oil-price implications. Summary: EIA estimated 7.5 mb/d of shut-in crude in March 2026, rising to 9.1 mb/d in April, and said Brent averaged $103/bbl in March. It forecast Brent to peak at $115/bbl in 2Q26, average $96/bbl in 2026 and $76/bbl in 2027, with only a sub-$90 print expected in 4Q26. Even under its assumption that the conflict would not persist past April, the forecast never approached $50.
7. “Major Wall Street Banks Lift Oil-Price Forecast, Survey Shows — Commodities Roundup” — MarketScreener/Dow Jones; published Sept. 30, 2026. Description: Survey of Goldman Sachs, JPMorgan, Morgan Stanley and other bank oil forecasts. Summary: The survey showed major banks raising their 4Q26 Brent forecast to an average $90.22/bbl from $78.92 and their full-2026 forecast to $88.13/bbl. The 1Q27 consensus was $83.44/bbl for Brent and $79.88/bbl for WTI, still far above $50 after allowing for recovering Middle East exports. Even the lowest cited consensus point is roughly 67% above the resolution threshold.
8. “OPEC+ Expected to Keep Oil Production Quotas Unchanged” — OilPrice.com; published Sept. 29, 2026. Description: Report on OPEC+ quotas, actual Gulf production and Iran-war supply disruption. Summary: OPEC+ was expected to hold November 2026 quotas unchanged after six monthly increases, with actual Gulf supply still far below headline quotas because of the Iran war and Hormuz disruption. OPEC+ output was 38.05 mb/d in August 2026, about 5 mb/d below pre-war levels, while roughly 2 mb/d of cuts remained in force through end-2026. That physical tightness supports prices well above $50 despite nominal quota increases.
9. “3 Bold Oil Market Predictions for 2026” — Nasdaq; published Jan. 2, 2026. Description: Early-2026 bearish oil-market outlook that explicitly raised the sub-$50 scenario. Summary: Nasdaq featured a call that Brent would fall below $50 at some point in 2026 before recovering, based on a projected supply glut. It cited EIA’s then-forecast of about $55/bbl for 1Q26 and Goldman Sachs’s $56/bbl 2026 average, with downside to $51 if a Russia-Ukraine peace deal materialized. That was the clearest early-year Yes case, but it predated the Iran war and was contradicted by the subsequent $59.73 low and $110+ October price.
10. “PredictMarketCap — Oil Markets” — Multi-platform prediction-market dashboard; accessed Oct. 20, 2026; no publication date shown. Description: Aggregates Hyperliquid futures and Kalshi/Polymarket strike contracts into implied oil-price distributions. Summary: At access, the dashboard showed Hyperliquid Brent at $106.61 and WTI at $99.55, with $17.61 million in tracked volume. Its Dec. 31, 2026 Brent-implied distribution had a $115.01 mode, $135 mean and $65–$180 10th–90th percentile range. No clean Brent sub-$50 contract was visible, and the 10th percentile is $15 above the threshold, making this weak but directionally No evidence.
Resolution snapshot
| Metric | Latest value |
|---|---|
| Resolution trigger | Brent below $50 at any point in 2026 |
| Trading Economics Brent, Oct. 20, 2026 | $110.50/bbl |
| Lowest 2026 weekly low shown | $59.73 (week of Jan. 5) |
| Trailing 52-week low | $58.69 (mid-Dec. 2025) |
| Trailing 52-week high | $119.46 (March 2026 futures) |
| Decline needed from $110.50 to $50 | −54.8% |
| Trading days/days remaining | About 72 calendar days |
This is a source rundown, not a probability forecast.
Extracted resolution criteria links:
[‘https://tradingeconomics.com/commodity/brent-crude-oil‘]
=== Forecast Result ===
=== Reasoning ===
Analysis and Rationale
1. Current Baseline and Distance to Threshold
- Current Status: As of October 20, 2026, Brent Crude is trading at approximately $110.35–$110.50/bbl on Trading Economics (the designated resolution source).
- Year-to-Date Low: The lowest weekly print in 2026 occurred during the first week of January at $59.73/bbl, and the trailing 52-week low is $58.69/bbl. During the summer dip following temporary de-escalation, Brent bottomed around $70.10/bbl. At no point in 2026 has Brent traded below $50.
- Required Move: To trigger a “Yes” resolution before December 31, 2026 (72 calendar days / ~51 trading days), Brent must decline by at least $60.50/bbl, or −54.8%.
2. Market Fundamentals and Catalysts
- Supply Deficit & Physical Tightness: The IEA and EIA both confirm that global balances remain in physical deficit through the end of 2026. Global inventories are depleted (>500 million barrels below early-year levels), Middle East production is constrained by ongoing conflict, and roughly 2 mb/d of OPEC+ cuts remain in place.
- Near-Term Outlook: Institutional forecasts for Q4 2026 cluster between $90 and $114/bbl (EIA raised its Q4 forecast to $105; Trading Economics models $113.86).
- What Would It Take to Breaching $50 in 72 Days?
- An immediate, total cessation of hostilities in the Middle East and swift, unimpeded reopening of the Strait of Hormuz.
- Immediate return of shut-in crude production and an aggressive OPEC+ market-share price war.
- A severe, synchronous global demand or liquidity shock (akin to October–December 2008).
Even during the sharp summer 2026 pullback, prices halted at $70 because physical restocking and refining demand created strong support.
3. Statistical and Barrier Analysis
- Volatility Analysis: Over a 72-day horizon (~0.20 years), assuming a high annualized volatility regime of 50%, one standard deviation is roughly 22.4%. Hitting $50 requires a log-return change of $\ln(50 / 110.5) \approx -0.793$, representing a $\approx -3.54\sigma$ move.
- In standard log-normal diffusion with a reflection barrier, the probability of touching that level is under 0.1%. However, commodity markets exhibit fat tails and jump-diffusion risks. Accounting for extreme tail jumps and market-structure shocks elevates this probability into the low single digits (~1.0%–2.0%).
- Data Feed / CFD Flaw Risk: Trading Economics tracks CFD/OTC quotes, where flash wicks, rolling artifacts, or transient pricing glitches can occasionally occur, adding approximately 0.5% of idiosyncratic resolution risk.
4. Comparison Across Timeframes
- Next 1 month (by Nov 20, 2026): < 0.5% (insufficient time for logistical supply restoration and severe inventory accumulation).
- Remaining 2026 (by Dec 31, 2026): ~2% (requires an extraordinary combination of geopolitical peace, OPEC+ quota breakdown, and macro crisis).
- Next 12 months (by Oct 2027): ~15%–20% (supply additions projected by IEA for 2027 and weakening demand growth give a plausible runway for a sub-$50 cyclical bear market).
5. Key Assumptions and Failure Modes
- Middle East supply constraints and geopolitical risk premium persist through year-end: Failure probability $\approx 5\%$. Even if full peace is achieved tomorrow, prices would realistically settle in the $65–$75 range before year-end rather than immediately collapsing to $50.
- Global macroeconomic stability avoids a 2008-style acute liquidity freeze in the next 10 weeks: Failure probability $\approx 2\%$.
- Trading Economics price feed does not suffer an erroneous flash-crash wick below $50: Failure probability $\approx 1\%$.
Accounting for these tail risks, the overall probability remains firmly in the low single digits.
Data sufficiency: Sufficient
Probability: 2%
End
About The Author