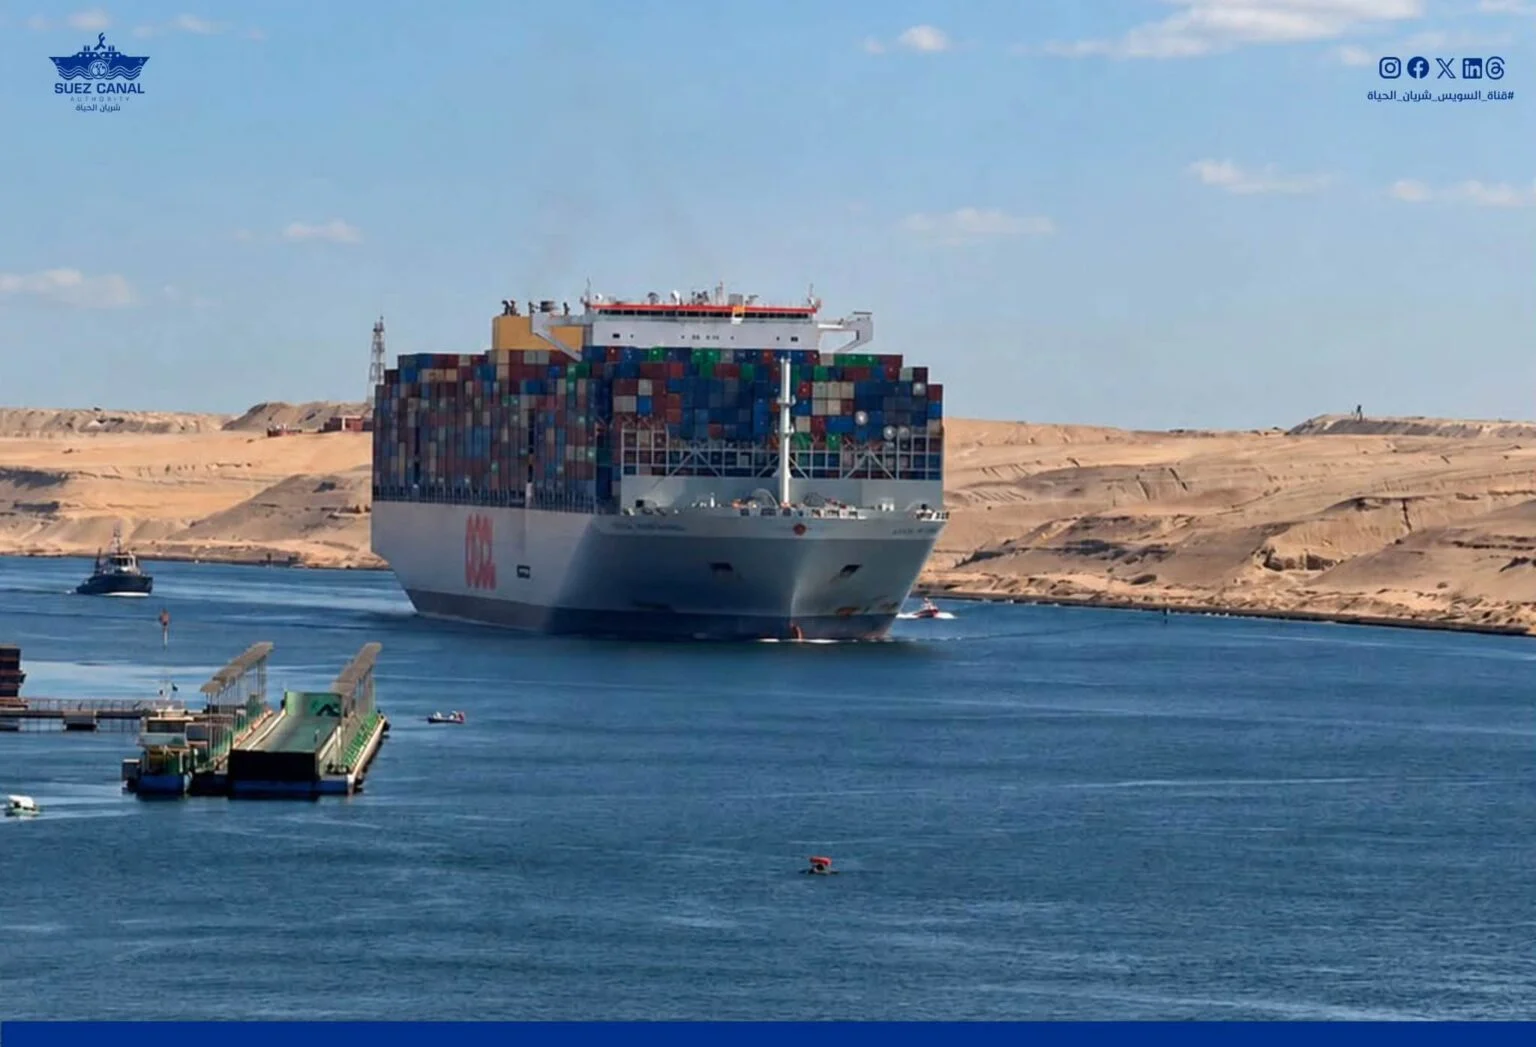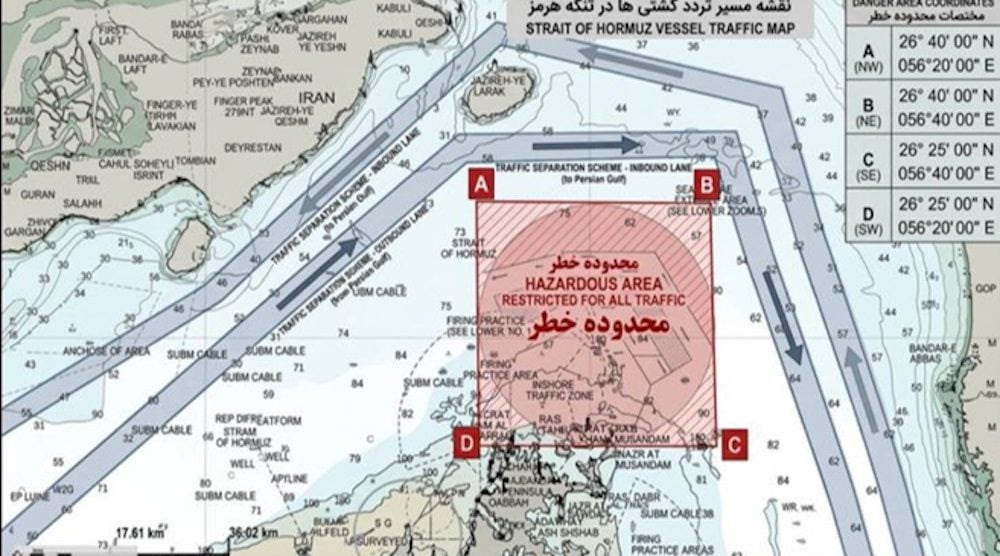
Iran said it will announce a new restricted zone in the Gulf in the coming days, along with maps of a new shipping corridor through the Strait of Hormuz. Source: https://gcaptain.com/iran-says-to-announce-new-restricted-zone-in-the-gulf-in-the-coming-days/
Grok response:
10 Citations
- Title: Brent oil – Price – Chart – Historical Data – News
Description: Trading Economics commodity page tracking Brent crude prices, stats, and model-based forecasts (resolution source).
Date: September 8, 2026
Summary: Brent traded at 98.419 USD/bbl, up 1.29% on the day and 48.22% year-over-year, with a Q3 forecast of 97.409 and 12-month estimate of 113.59. Prices rose toward $99 after Saudi reports of Houthi attacks on energy facilities, adding to Hormuz and Iran war concerns. Historical all-time high was 147.50 in 2008; the page notes CFD/OTC data as a market reference.[1] - Title: Short-Term Energy Outlook
Description: U.S. EIA monthly forecast of energy markets, including Brent prices, inventories, and supply-demand balances.
Date: August 11, 2026 (forecast completed August 6; next release September 9)
Summary: EIA forecasts Brent averaging $87/bbl in 2026 and $69/bbl in 2027, with Q3 2026 around $85 and Q4 around $78 as inventories rebuild after Hormuz disruptions. Global inventories fell 4.2 mb/d in Q2 and are expected to fall another 3.8 mb/d in Q3; most Middle East production recovers in early 2027 with 0.6 mb/d lingering disruptions. Demand is seen at ~104 mb/d in 2026 amid high prices.[2] - Title: Goldman’s $120 oil scenario puts advisor portfolios on alert
Description: InvestmentNews report on Goldman Sachs updating crude forecasts amid Hormuz tensions.
Date: September 8, 2026
Summary: Goldman raised December 2026 Brent forecast to $85 (from prior) and 2027 to $80, with a $120 upside if 2027 Gulf output stays 4 mb/d below pre-war levels due to intensified attacks. Downside to $80 if exports normalize. Options-implied probability of Brent >$100 by March 2027 rose to ~25%.[3] - Title: Citi revises Q3 2026 Brent forecast to $80/bbl
Description: Reuters article on Citigroup’s updated oil outlook amid U.S.-Iran talks.
Date: August 7, 2026
Summary: Citi raised Q3 2026 Brent average to $80 from $75 due to prolonged dealmaking, while keeping Q4 2026 and 2027 at $70 and $65. Prices climbed on job data and negotiation worries; Goldman separately expected $80-90 range until a deal or escalation. Brent was at $81.79 at the time.[4] - Title: JP Morgan lowers Brent crude price forecast for second-half 2026
Description: Economic Times/Reuters report on JPMorgan’s H2 2026 revision.
Date: June 27, 2026
Summary: JPMorgan cut H2 forecasts to $86 Q3, $80 Q4, and $78 year-end 2026 due to weaker OECD inventory draws and larger demand losses than expected. It sees oversupply in Q4 2026/H1 2027 requiring curtailments; oil flows were running ~8.6 mb/d recently. 2027 average implied lower.[5] - Title: OPEC+ keeps output policy unchanged for October
Description: Energy Connects report on OPEC+ monthly decision.
Date: September 8, 2026
Summary: OPEC+ (core seven members) maintained September production levels for October amid Hormuz disruptions, after completing rollback of prior cuts. OECD inventories fell 26.4 million barrels in June to 2.73 billion; the group forecasts 2026 demand growth of 0.6 mb/d to 105.7 mb/d and 2.2 mb/d in 2027. Actual output remains below targets due to conflict.[6] - Title: Oil Market Report – August 2026
Description: IEA monthly analysis of global oil supply, demand, and balances.
Date: August 15, 2026
Summary: IEA forecasts world oil demand declining 1.6 mb/d in 2026 (revised down 510 kb/d) due to Hormuz closure and high prices, with contractions easing from 4.9 mb/d in Q2 to growth in Q4. OPEC+ crude production details show large shortfalls vs. targets (e.g., Saudi 8.24 vs. implied higher). Non-DoC supply grows modestly.[7] - Title: Brent Crude Oil Historical Prices – 12-Month Chart & Analysis
Description: OilPriceAPI summary of recent Brent price history, highs/lows, and averages.
Date: Circa September 2026 (data through Sep)
Summary: 12-month high $104.23, low $61.80, average $81.72; current ~$95.23, up 48.54% vs. year-ago $64.11. Monthly averages: Jan 2026 $64.22, Feb $69.21, March $99.37 (war onset spike), May $104.23, then summer dip to $83-87 before recent rebound. Range represents ~69% swing.[8] - Title: Crude Oil Brent US Dollars per Barrel January 2026
Description: Countryeconomy.com historical monthly/daily Brent spot prices.
Date: February 2, 2026 (covering January data)
Summary: January 2026 average $66.60 (up from December 2025 $62.54); daily prices ranged ~$61-72, with late-month close $72.25. Year-over-year down 16% at the time; subsequent months showed the March spike. Confirms early-2026 levels well above $50.[9] - Title: Some Middle East oil output will stay shut through next year, US EIA says
Description: Reuters recap of EIA August STEO details on shut-in production.
Date: August 11, 2026
Summary: EIA estimates 5.5 mb/d Middle East output shut in July (~5% of global demand); 0.6 mb/d disruptions persist through 2027 even after early-2027 recovery. Raised 2026 Brent to $86.81 average (from under $82); 2027 $69.39. Global output 100.8 mb/d vs. demand ~104 mb/d in 2026, creating deficit then surplus.[10]
News and Data: This is a market-price question resolving on Trading Economics Brent data if the price trades below $50/bbl at any point in calendar 2026. As of September 8, 2026 (current date implied by sources), it has not occurred year-to-date, and remaining time is ~3.5 months.
Current Price and Recent Moves (as of Sep 8, 2026): Brent is at 98.419 USD/bbl (Trading Economics CFD/OTC reference; similar futures ~98.5-98.6), up 1.29% on the day, 12.18% over the past month, and 48.22% year-over-year. It approached $99, the highest since July 23, after Saudi reports of Houthi attacks halting operations at southern energy facilities (including a 400,000 b/d Jazan refinery). Additional support came from Iran-Oman talks on a Hormuz safe-passage deal (raising control concerns) and stronger Chinese crude imports in August. WTI is around 93.8. The curve shows limited backwardation currently due to tightness.[1]
2026 Year-to-Date History, High/Low, and Volatility: Prices started 2026 in the low-to-mid $60s (January average $66.60, with daily lows around $61; February ~$69). A sharp spike occurred in March (monthly ~$99) with the onset of Iran-related conflict and Hormuz disruptions, peaking near $104-126 in spring (52-week high variously reported 119.50-126.41). Summer saw a pullback to the $80s amid U.S.-Iran deal hopes and some inventory/demand weakness, before the recent rebound to ~98. 52-week range is approximately 58.72-126.41 (low in late 2025/early 2026). No daily close or trade below $50 in 2026; the 12-month low is ~$58.7-61.8. Volatility has been extreme (~70% range in 12 months) driven by geopolitics rather than typical seasonality (Q4 winter demand usually supportive, but currently secondary). All-time high remains 147.50 (July 2008); long-term average ~71.[8]
Forward-Looking Forecasts and Wall Street Consensus (Q4 2026 and beyond): Authoritative sources do not project a drop below $50 in remaining 2026. EIA (August STEO, most recent official): 2026 full-year average $87 (or $86.81), Q3 ~$85, Q4 ~$78, then $69 in 2027 as inventories rebuild and most shut-in production (~5.5 mb/d in July) returns in early 2027 (0.6 mb/d lingering). This assumes gradual Hormuz recovery. Goldman Sachs (updated Sep 8): raised Dec 2026 to $85 and 2027 to $80; $120 bull case if Gulf output stays 4 mb/d below pre-war, $80 if normalizes. JPMorgan (June): Q3 $86, Q4 $80, year-end $78 (2027 ~$64). Citi (Aug): Q3 $80, Q4 $70, 2027 $65. Other June-era views (Morgan Stanley $75 Q3/Q4; Reuters poll of 31 analysts $84.50 full-year 2026 with Q4 ~$79) have been overtaken by renewed tensions. Trading Economics model is more bullish (Q3 97, 12-month 114). Consensus for remaining 2026 clusters 70-85, with surplus expected late 2026/2027 from non-OPEC growth (U.S., Brazil, Guyana) plus any Hormuz reopening, but current tightness and attacks keep near-term support. No major bank sees sub-$50 this year.[2]
Supply, Demand, and Geopolitical Context: IEA sees 2026 demand down 1.6 mb/d (high prices + disruption, especially Asia/China EVs/alternatives); OPEC+ sees modest +0.6 mb/d growth to 105.7 mb/d then +2.2 in 2027. OPEC+ held October quotas unchanged (Sep 6/8 meeting) after symbolic increases; actual output lags due to conflict. EIA notes large Q2/Q3 inventory draws (4.2 then 3.8 mb/d), OECD stocks low. Non-OPEC supply growth continues. [7]
Extracted resolution criteria links:
[‘https://tradingeconomics.com/commodity/brent-crude-oil‘]
=== Forecast Result ===
=== Reasoning ===
Brent is currently near $98/bbl, and the event has not occurred during 2026 despite substantial volatility. The remaining window is only about three and a half months. A move below $50 would require roughly a halving from current levels, substantially larger than the recent summer pullback and well below the bearish Q4 forecasts, which generally remain around $70–80.
The principal route to a Yes outcome would be a combination of rapid Middle East de-escalation, restoration of disrupted supply, unexpectedly severe demand destruction, and/or a global recession or financial shock. A brief intraday wick below $50 is easier than a sustained decline, especially because the resolution source references a market-price series, but even that would require an unusually large move.
Approximate conditional timing assessment:
- By the end of October: 1%
- By the end of November: 2%
- By the end of December: 3%
Key assumptions and estimated chances they are wrong:
- No extreme global recession, pandemic-like demand shock, or financial crisis occurs: 95% confidence. Failure would materially increase the probability.
- Geopolitical normalization, if it occurs, produces a moderate decline rather than an enormous oversupply shock: 88% confidence. Failure could make a sub-$50 print plausible.
- The Trading Economics series does not register an anomalous data error or unrepresentative flash print: 98% confidence.
The base case is therefore a continued high-price regime or a decline into the $60–80 range, not a breach of $50. I assign a low-single-digit probability to the threshold being crossed, with some allowance for extreme commodity-market tail risk.
Data sufficiency: Sufficient
Probability: 3%
End
About The Author